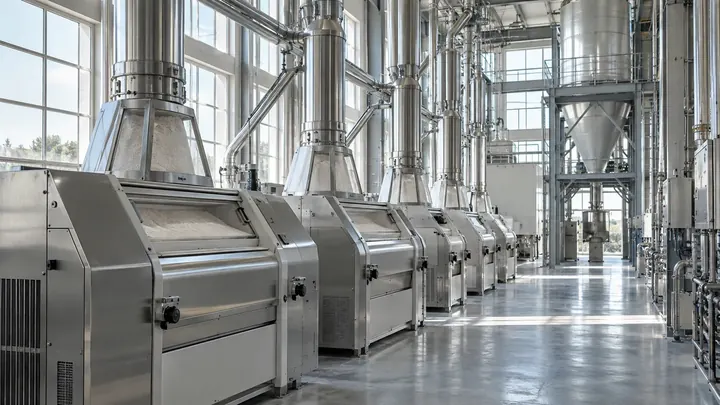
A toll mill processes material for another party under an agreed service arrangement. Its revenue may be a fee rather than ownership of the finished product, making custody and quantity records especially important. The contract should explain what arrives, what work is performed and how every relevant output or loss is treated before customer material enters shared equipment.
Define the property and service boundaries
The parties should record ownership, custody points and the work included in the fee, with appropriate legal review for their circumstances. A label such as toll milling cannot settle those terms. FAO's grain-processing resources provide context for the transformation of input into several output streams. The service agreement needs a specific account of the intended line and product. It should identify which materials the customer supplies and whether packaging, testing, storage and dispatch are included or require separate arrangements and charges.
Customer material should also remain identifiable in insurance and loss reporting under the agreed arrangements. The mill and owner need to understand which party reports an event and supplies evidence, rather than discover that interface only after material is missing or damaged.
Agree the physical reconciliation
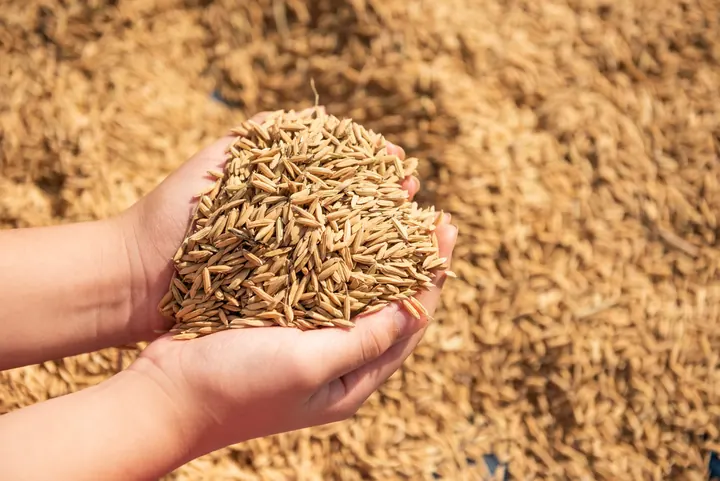
A hypothetical customer delivers paddy and expects finished rice plus an agreed treatment of bran, husk and other outputs. The contract should define measurement bases and how differences are assessed, using technical methods appropriate to the material. A guaranteed conversion should not be inferred from a catalogue capacity or a generic industry yield. Representative trials and clear input conditions can inform negotiations. The record needs to connect each customer's incoming material with the authorised processing and outgoing quantities rather than use an aggregate mill balance that cannot explain individual work.
Plan segregation and scheduling
Shared storage and machinery create practical questions about identity, transitions and order priority. The operator should have approved procedures for preserving the agreed distinctions. Small toll jobs can carry substantial handling and changeover costs, so the commercial terms need minimum runs or an appropriate alternative charging basis. Customer delays in collecting output should also have a defined treatment. A nominally attractive fee can leave the mill holding stock or losing capacity needed for another commitment if these obligations are not priced and scheduled.
Close the job with a usable statement
The completion account should identify received quantities, services, outputs, adjustments and any unresolved item. Both parties need a route to review discrepancies while relevant evidence remains available. The mill should distinguish its fee revenue from the value of customer-owned inventory in internal reporting. A dependable toll arrangement can provide useful utilisation, yet its economics depend on the service actually sold. Clear custody and reconciliation allow the operator to explain its contribution without treating all material passing through the plant as its own commodity sale.